Chest: The Pension App That Turns Everyday Spending Into Retirement Savings
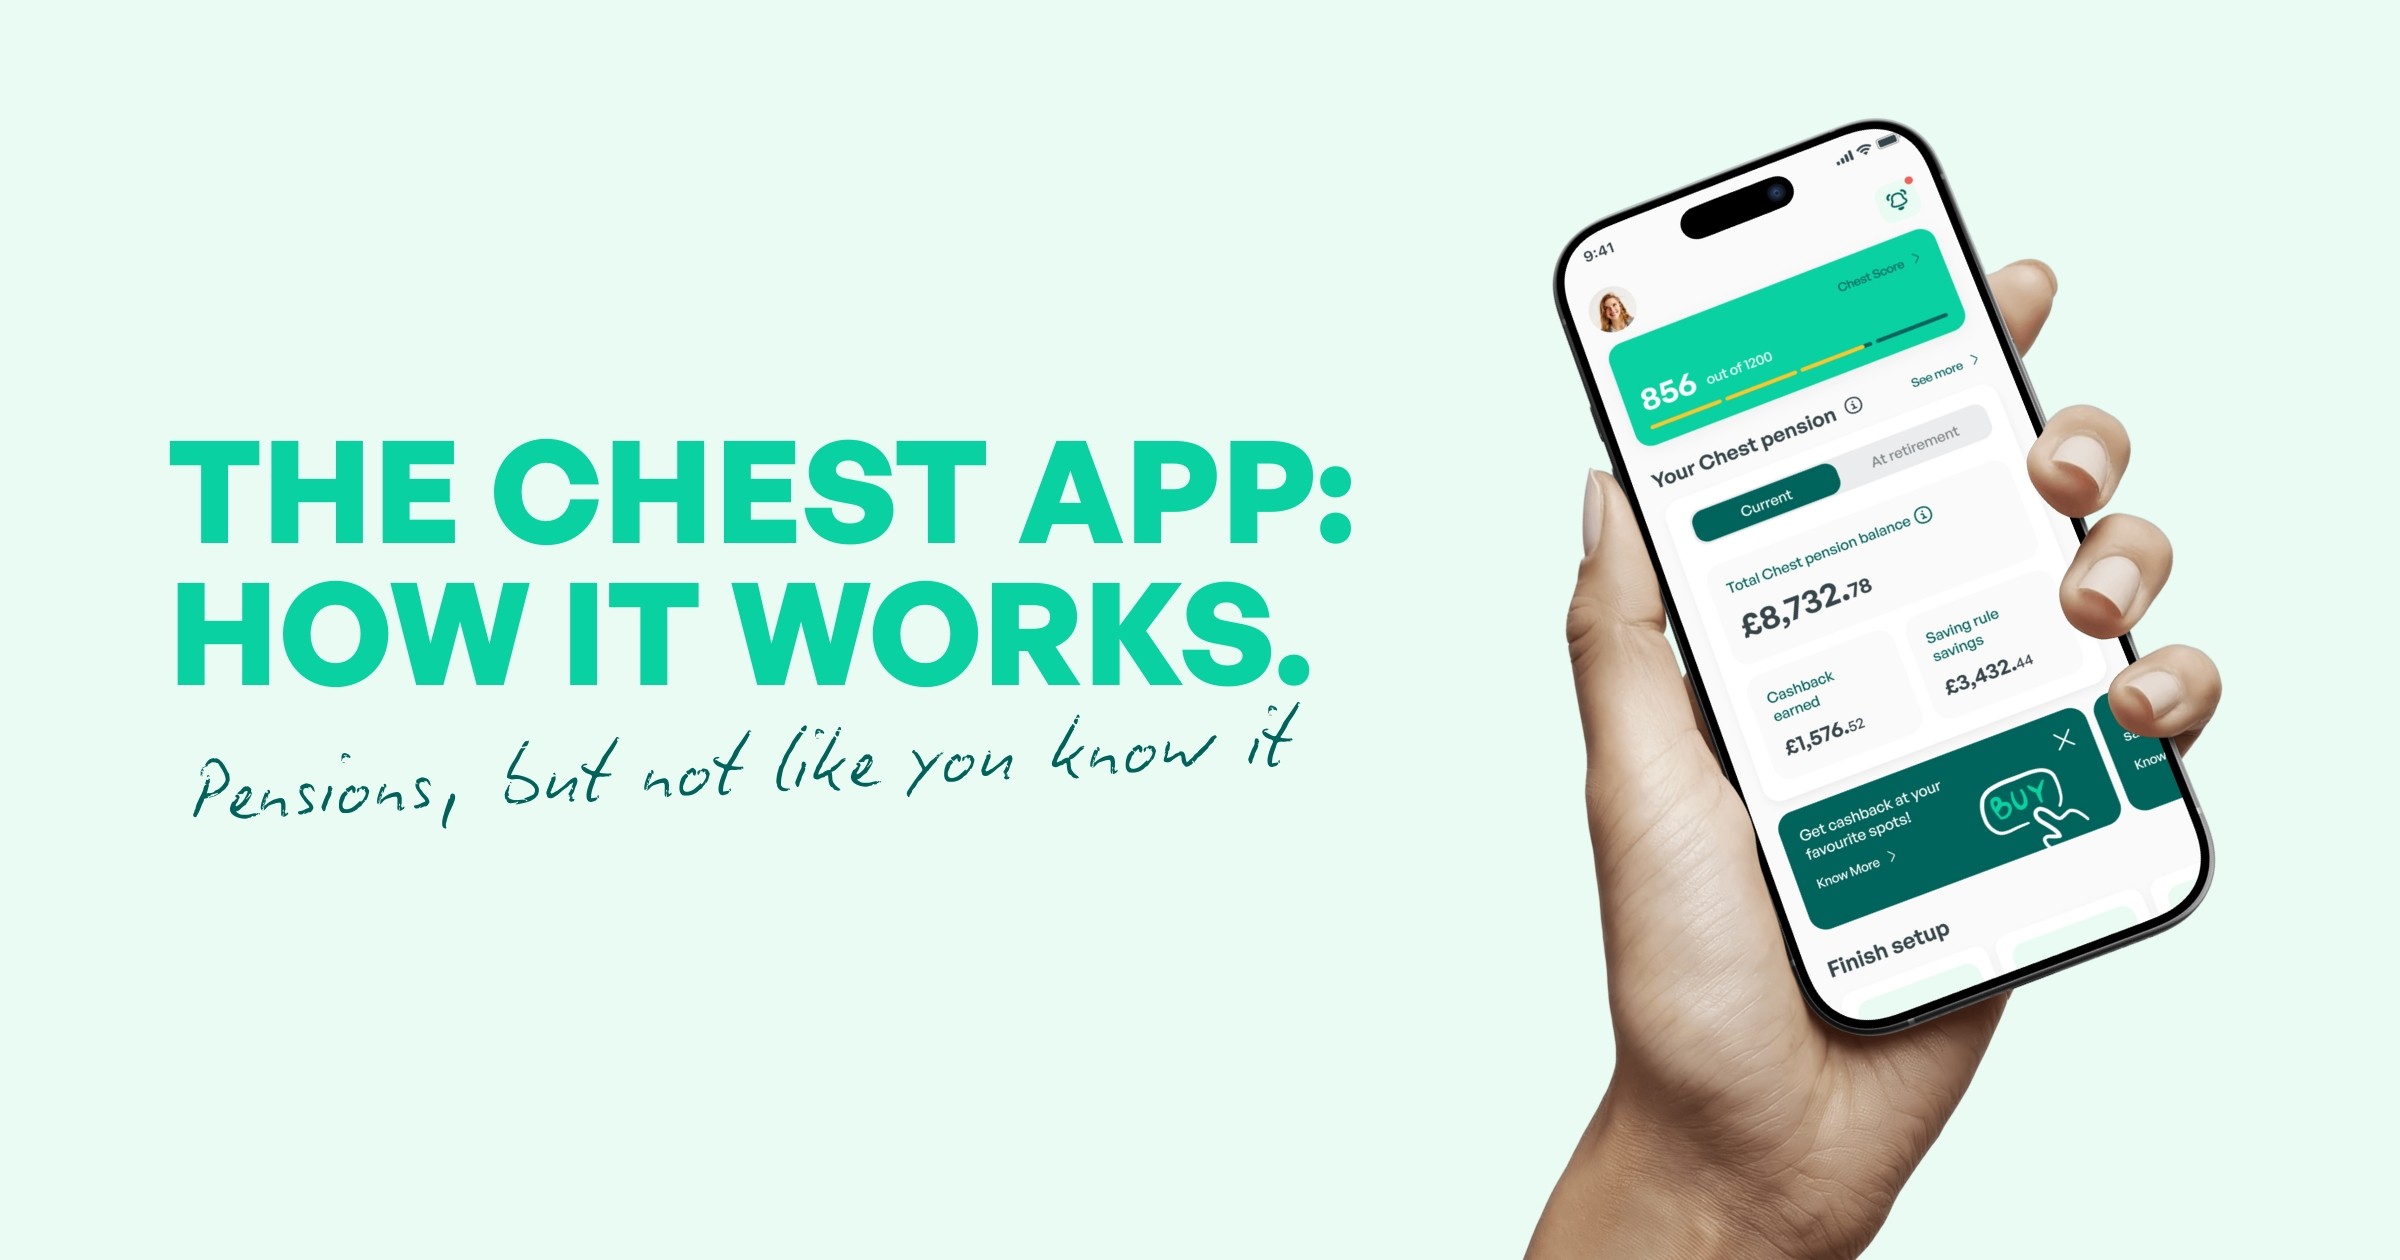
The short answer: Chest is a pension app that pays cashback from your everyday shopping into your own personal pension (a SIPP). In 2026/27, basic-rate tax relief adds 25% on top, so £10 of cashback becomes £12.50 in your pot. You can also set saving rules, check your Chest Score and bring old pensions together.
How does Chest work?
When you sign up, Chest sets you up with a self-invested personal pension (SIPP). That's a personal pension you arrange yourself, in your name, and you manage it in the app. GOV.UK explains that a SIPP lets you control the investments that make up your pension, and that the money you pay in is invested, so its value can go up or down.
Capital at risk. The value of your pension can go down as well as up, and you may get back less than you pay in.
Already got a workplace pension? Keep it. Chest isn't there to replace it. As the Chest homepage says, your Chest pension can sit alongside your employer's scheme, so you can build extra savings on top of what you already pay in through work. A workplace pension is arranged by your employer, while a SIPP is one you choose yourself. If you're weighing up the two, our guide on SIPPs and workplace pensions explains how they can work together.
Chest is open to UK residents aged 18 or over. You get three ways to grow your pot:
Pension cashback when you shop with partner brands.
Saving rules that put money aside automatically.
Pension transfers, to bring old pots into one place.
Cashback paid into a pension gets tax relief, which is where it gets properly interesting.
Tax treatment depends on the individual circumstances of each client and may be subject to change in future.
Why is saving for a pension so hard?
Because the bills are here now and retirement feels a long way off. Rent, food and the odd surprise tend to win every time. It's hard to care about something decades away when your washing machine has just given up.
You're far from the only one:
Scottish Widows' 2025 Retirement Report found that 42% of people in their 20s are at risk of poverty in retirement.
Research by Aegon, reported by Pensions Age, found only 12% of people put pension saving in their top three money priorities for 2026.
An analysis of HMRC data by Bowmore Financial Planning found people in their 20s who pay into a defined contribution pension save £721 a year on average, about 2.5% of their salary.
If that sounds familiar, you're not behind because you did something wrong. The system was built for a different time. That's why we built Chest: to fit saving into the life you already have.
How does pension cashback work?
You shop as normal with one of 160+ brand partners, and the cashback goes into your Chest pension instead of your current account. Need new trainers? That's a pension contribution. Fancy a pizza? That's future you's treat.
Here's how it works today, according to the Chest brands page and Chest FAQs:
Browse. Pick a brand in the app, from groceries and dining to fashion and travel.
Buy a Chest Code. Choose any amount and pay from your bank account using Open Banking. The code is ready straight away.
Pay in-store or online. Scan the code at the till or enter it at checkout. It works like a gift card, and any unused balance stays on it.
Grow. The cashback rate shown in the app is applied, and Chest pays the cashback into your pension on your behalf, where it's invested.
Cashback rates vary by brand, with rates up to 19.5%. Brand partners and rates can change, and cashback contributions are discretionary. You can track your cashback, and what it could be worth at retirement, in the app.
How much does tax relief add to your cashback?
For a basic-rate taxpayer, tax relief adds 25% to every pound of cashback paid into your pension. That's because Chest is a personal pension, and GOV.UK says personal pensions use "relief at source": your provider claims tax relief from the government at the basic 20% rate and adds it to your pot.
Twenty per cent of the total is the same as 25% on top of what you paid in. So:
£10 of cashback becomes £12.50 in your pension.
£100 becomes £125.
If you pay Income Tax above the basic rate, you can claim more. In England, Wales and Northern Ireland, you claim an extra 20% on income you paid 40% tax on, and an extra 25% on income you paid 45% tax on, through your Self Assessment tax return. If you don't file a return, GOV.UK explains other ways to claim. Scotland has different rates, so check the GOV.UK page if you live there. For more on how this works, read our simple guide to personal pensions and tax relief.
Example: £20 a month of cashback, worked through
These are round, made-up numbers to show the maths. They ignore investment growth and charges.
You earn in cashback | Basic-rate relief added | Goes into your pot |
|---|---|---|
£20 a month | £5 | £25 |
£240 a year | £60 | £300 |
£2,400 over 10 years | £600 | £3,000 |
This assumes you're a basic-rate taxpayer and stay within the tax relief limits below. It turns Friday's takeaway into Monday's pension top-up, which is about the closest thing to a legal life hack we know.
Is there a limit on pension tax relief?
Yes, but most people won't get near it with cashback. GOV.UK sets two main limits:
Your earnings. You can get tax relief on pension payments worth up to 100% of your annual earnings in a year.
The annual allowance. This is the most you can pay into all your pensions in a tax year before you pay tax. It's £60,000 for 2026/27, and it counts money paid in by you and anyone else, like your employer.
If you earn little or nothing, you can still get relief. Your provider can claim 20% on payments up to £2,880 a year if you have no earnings, which becomes £3,600 with relief added.
A few other rules can lower your allowance. The annual allowance page explains the taper for very high earners and the carry forward rule. And if you've already started taking money flexibly from a pension, a lower money purchase annual allowance of £10,000 applies.
How do Chest saving rules work?
Saving rules put money into your pension automatically, so you don't need willpower or reminders. You link your bank account using Open Banking, which the Chest FAQs describe as a secure, regulated way to connect your bank to approved apps. Then you pick your rules and they run in the background.
You can choose from:
Round-ups. Each purchase is rounded up to the nearest pound and the spare change is saved. Buy a £3.80 coffee, save 20p.
Monthly depositor. A fixed amount you choose, saved each month.
No spend challenge. Save a set amount on any day you don't spend from your linked bank account.
Chestflix and Chill. Save the same amount as a monthly streaming subscription.
You're always in control: you can pause, adjust or turn off your rules at any time. Curious how much spare change adds up to? Our guide to how pension round-ups work walks through it.
What is the Chest Score?
Think of it as a credit score for your pension. It's one number that shows how prepared you may be for the future, so you can see where you stand without wading through old statements. A bit like a step counter, but for retirement, and with less guilt after a lazy Sunday.
It's for information only, and it shows estimates rather than promises. What you end up with depends on what you pay in, how markets perform, charges and the assumptions used.
Can I bring my old pensions into Chest?
Yes. You can transfer personal pensions and old workplace pensions from previous employers into your Chest SIPP. Got a pot from that summer job, another from a temp role and a mystery one from a gig you left after a month? They're not lost, just a bit emotionally distant.
According to the Chest FAQs:
Chest doesn't charge to transfer a pension in, but your current provider might charge an exit fee.
Transfers usually take 2 to 6 weeks, and can take longer if more information is needed.
You can transfer more than one pension.
You can't transfer your current workplace pension with your existing employer, only pensions from previous jobs.
Moving a pension isn't right for everyone, so check first. MoneyHelper says a transfer usually can't be undone. Check whether your old pension has special features or guarantees, or exit fees. If you have a defined benefit (final salary) pension worth over £30,000, you'll need to pay for financial advice before you can move it to a pension like a SIPP.
Lost track of an old pot? The government's Pension Tracing Service can find contact details for a scheme if you know the employer or provider's name. GOV.UK also has free information on transferring your pension. For a step-by-step look, see our guides to pension consolidation and transferring your pension to a SIPP.
When can I take money out of my Chest pension?
Usually not before age 55. GOV.UK says you can usually take money from your pension pot after you're 55, depending on the scheme's rules. That minimum age is rising to 57 from 6 April 2028.
So your cashback is locked away for later life, and you can't dip into it for next month's holiday. That's the whole idea, but it's worth knowing before you start.
Is Chest available now?
Chest is in beta testing right now, so the team can fine-tune the app and gather feedback before the public launch, as the Chest FAQs explain. You can join the beta to be one of the first to use it.
Until then, the steps above show how it will work, so you'll know what to expect on day one.
Still got questions?
Is Chest regulated? Chest Group Limited is an appointed representative of RiskSave Technologies Ltd, which is authorised and regulated by the Financial Conduct Authority (firm reference 775330), as set out on the Chest website.
Do I need to spend more to earn cashback? No. The idea is to earn cashback on things you'd buy anyway. Spending more than you planned just to earn cashback won't leave you better off.
Can I have a Chest pension and a workplace pension at the same time? Yes. Chest is designed to sit alongside a workplace pension. Both count towards your £60,000 annual allowance.
Is a SIPP better than a workplace pension? They do different jobs. A workplace pension usually comes with money from your employer, so it's worth checking what you'd give up before changing anything. Everyone's situation is different, so we can't say what's right for you. MoneyHelper offers free, impartial guidance.
What if I don't pay Income Tax? You can still get basic-rate relief at source on payments up to £2,880 a year if you have no earnings, or up to 80% of your earnings if you earn but pay no Income Tax.
Does the Chest Score tell me what I'll retire with? No. It's an estimate for information only, and it isn't a guarantee.
Sources
Scottish Widows: Retirement Report 2025 press release (7 May 2025)
Pensions Age: Pension saving slips down priority list as short-term pressures dominate financial planning (12 January 2026)
IFA Magazine: New analysis of HMRC data shows people in their 20s save only 2.5% of their earnings into pensions (27 May 2025)
GOV.UK: Personal pensions (accessed 7 October 2026)
GOV.UK: Workplace pensions (accessed 7 October 2026)
GOV.UK: Tax on your private pension contributions (accessed 7 October 2026)
GOV.UK: Tax relief on private pension contributions (accessed 7 October 2026)
GOV.UK: Annual allowance (accessed 7 October 2026)
GOV.UK: Pension schemes rates and allowances (updated 6 April 2026)
GOV.UK: Early retirement, personal and workplace pensions (accessed 7 October 2026)
GOV.UK: Increasing normal minimum pension age (accessed 7 October 2026)
GOV.UK: Transferring your pension (accessed 7 October 2026)
GOV.UK: Find pension contact details (accessed 7 October 2026)
MoneyHelper: Should I transfer or combine my pensions? (accessed 7 October 2026)
Chest: Home (accessed 7 October 2026)
Chest: Cashback brands (accessed 7 October 2026)
Chest: FAQs (accessed 7 October 2026)